GSTArk® — Intelligence Activating
AI-Powered GST Decision & Verified Legal Intelligence

The GST proceeding, argued end to end.

Specialist drafting benches for every stage of a GST matter, a decision environment built around every draft, and a knowledge tree where each section carries its verified rules, notifications, circulars and judgments. Built with former CGST officers, practising advocates and GST litigation specialists who work GST matters.

Every citation verified or flagged · Answers as the law stood on the relevant date · Human review always
Workflow BenchesExpert Built-in PromptsEditable A4 DraftsFinancial AnalysisNotesheet SupportGSTAT LitigationVerified Source Layer

GST Latest News

Latest circulars, rulings, case law

No bench required

Not sure a bench fits? Start in the open workspace.

A clean AI workspace for the miscellaneous work a bench does not cover: a quick opinion, a calculation, a plain letter, a second read on a clause. GSTArk keeps its GST knowledge and its verified sources; you keep the freedom of a blank page.
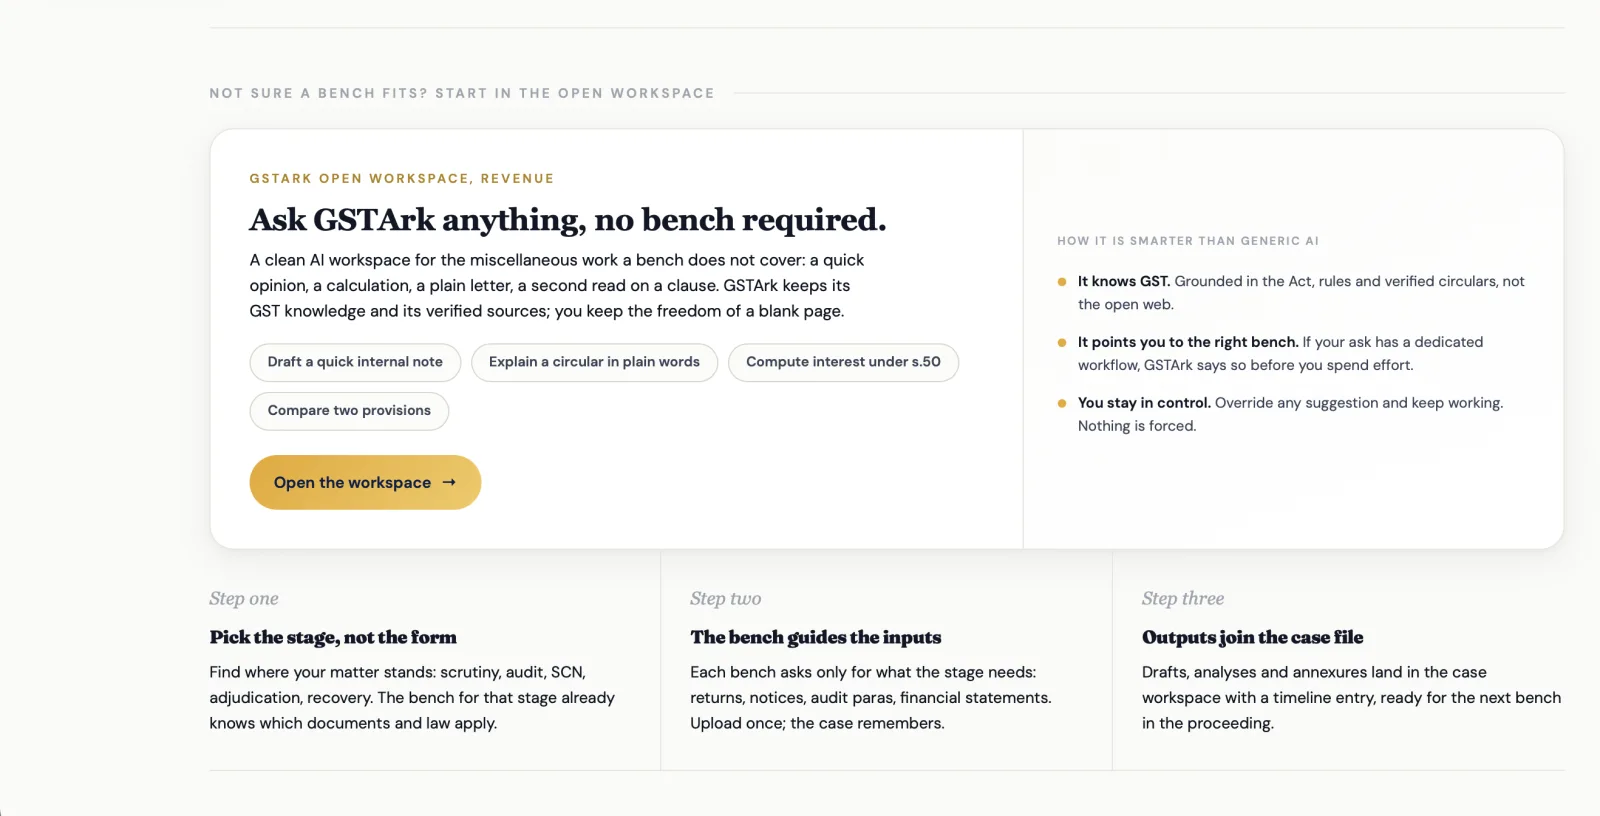
gstark.ai / dashboard · Open workspace
GSTArk open workspace (revenue): Ask GSTArk anything, no bench required, with example asks and the three steps: pick the stage, the bench guides the inputs, outputs join the case file
The Five-Stage Case Journey

One matter, one thread: the case moves with you until a definite outcome

Every stage inherits the facts, record and statutory history of the one before in an append-only case ledger.

1 · Trigger
Notice received
DRC-01, s.74 · limitation clock armed on day one
2 · Bench
SCN Reply Bench
Curated prompts, grounded record, exact A4 draft
3 · Decide
Decision Room
Probability, exposure, opponent's clock, omissions
4 · Contest
Adjudication, Appeal
The file and its history travel to the next bench
5 · Close
Definite outcome
Order accepted, dropped or carried up; ledger closed
Engines around every draft:ProbabilityExposureMove treeOpponent's clockAttack surfaceOmissions (both sides)Precedent mapNotesheetTimeline
247
Statute sections indexed
190 CGST · 28 IGST · 29 UTGST
213
CGST Rules
Current & Amendment-Aware
13
Specialist Benches
Revenue & Taxpayer Practice
12
Agents in development
Human review mandatory
15,023
Verified Authorities Live
Judgments · Circulars · AAR
The Platform

Not a chatbot. A chambers.

Every capability sits where a practitioner would expect it: benches for drafting, a decision room for judgment, a tree for the law, a dashboard for the clock.

Specialist Benches13 Benches

A dedicated bench for every stage, both sides of the table

Scrutiny, SCN drafting and reply, adjudication, refunds, audit, appeals, advance ruling and more. Each bench carries an inbuilt prompt framework and a GST legal skill curated by expert practice.
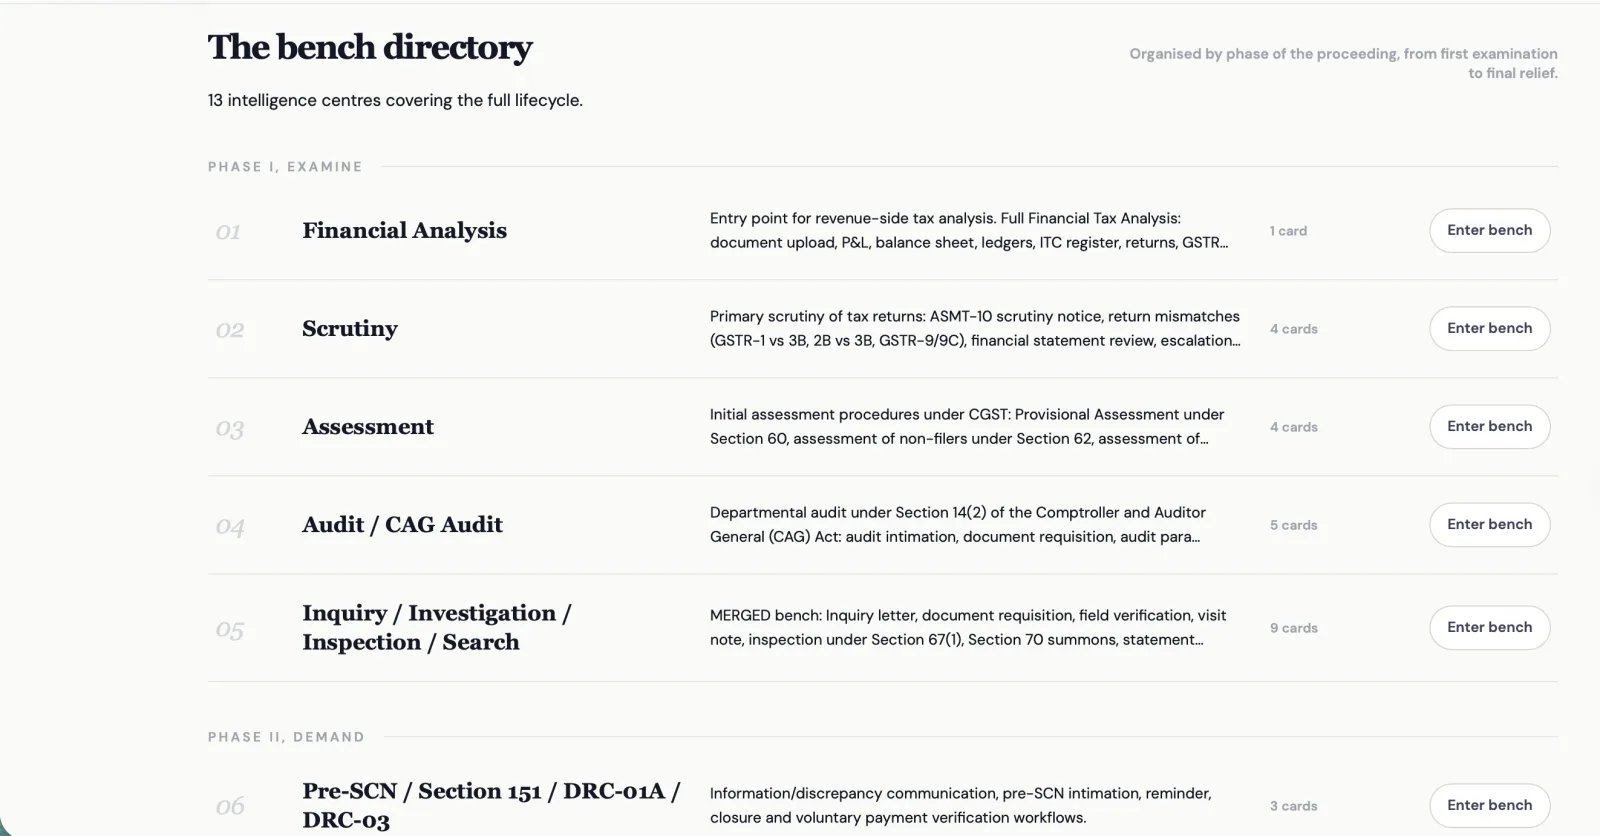
gstark.ai / dashboard · The bench directory
GSTArk bench directory: 13 intelligence centres covering the full lifecycle, organised by phase of the proceeding, from Financial Analysis, Scrutiny, Assessment, Audit and Inquiry in Phase I to Pre-SCN in Phase II
GSTArk FreeOpen Access

A generic AI workspace, still grounded in GST

Chat freely: attach PDFs, images and Excel, use the camera on a notice, copy and regenerate. When a specialist task is detected, GSTArk names the bench and what it adds; you can always generate here anyway.

✓ Section 74 CGST Act verified
✓ Allahabad HC (2024) cited
⚠ Circular 47/2022 flagged unverified
Decision RoomPreflight Engine

The draft is the start, not the end

Around every output: success probability, financial exposure, the department's likely next moves, the other side's limitation clock, and what your draft omitted, argued from both sides.

Defensibility Score78% Strong
Exposure Principal₹2.89 Cr
Live DashboardClocks Armed

The limitation clock, always armed

Every dated proceeding builds its timeline. The dashboard leads with what must move first and the last dates that cannot slip.

6d
Reply to DRC-01 falls due.
Act before 28 Oct.
Knowledge Tree247 Sections

The statute as a living tree

247 sections across CGST, IGST and UTGST, each node carrying its rules, notifications, circulars and judgments, opening into a full statute spine with the source text alongside.

• Section 16 CGST Act
↳ Rule 36 & Rule 37 attached
↳ Circular 183/15/2022 attached
Temporal LawAmendment-Aware

Answers as the law stood on the relevant date

GST law moves; your matter is judged on the law of its day. GSTArk's models are amendment-aware: the provision, rate and rule applied are the ones in force for the disputed period, not today's text pasted backwards.

Period under dispute: FY 2021-22
Applies Section 16(2)(aa) post 01.01.2022 amendment.
Exact A4, Editable

Output you can file, not paste and pray

Exact A4 paged preview, editable in place, refine by instruction, notesheet engine for the file, and DOCX export from every bench. What you see is the page that prints.
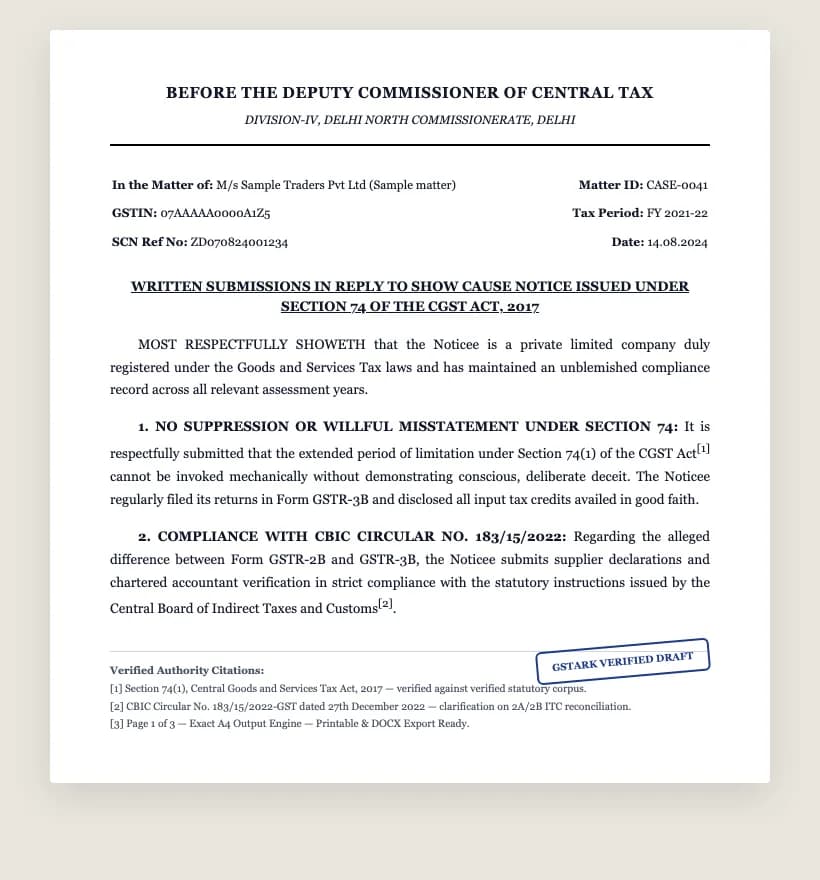
A4 PaginatedIn-place RefinementVerified CitationsDOCX & PDF Export
Exact A4 Paginated Draft Output — Speaking Reply
The Difference

Not Generic AI. GST Workflow Intelligence.

Generic AI tools need you to prompt them. GSTArk gives you structured GST workflows, built-in expert logic, editable A4 drafts and source-aware output.

Prompting model
Generic AIBlank text input box. The user has to explain the legal procedure and posture from scratch.
GSTArk ChambersStructured benches for SCN, OIO, audit, scrutiny, appeal, GSTAT, refund, recovery and more. Revenue and taxpayer modes are separate.
Source reliability
Generic AIMay hallucinate citations, section numbers and case references. No source verification.
GSTArk ChambersSource-aware drafting using verified GST layer — Acts, rules, circulars, notifications, judgments and instructions. Missing authority flagged.
Output format
Generic AIGeneric text block. No legal format. No A4 structure. No portal summary logic.
GSTArk ChambersEditable A4 legal workspace — Edit Draft, Custom Instructions, Save Version, Copy or export. Portal summary for DRC/APL where applicable.
Notesheet and financial integration
Generic AINo notesheet mode. No financial analysis. No exposure or reconciliation support.
GSTArk ChambersDepartment-side notesheets, internal notes, financial analysis reports, exposure mapping and reconciliation — built into the drafting workflow.
Decision intelligence
Generic AIGives isolated text. No limitation analysis, no natural justice check, no mens rea or evidence sufficiency review.
GSTArk ChambersBuilt-in decision intelligence: limitation, natural justice, mens rea, evidence sufficiency, litigation risk, appeal sustainability, document gaps and source confidence.
Chambers Architecture

Built for every requirement of indirect tax litigation.

Every card, prompt, calculation and citation maps to statutory provisions across the CGST, IGST, and UTGST Acts.

🧠

Expert Inbuilt Drafting Prompts

Every bench carries built-in GST expert prompt logic. Dropdowns change legal posture and output package without prompt engineering.

📊

Financial Document Analysis

Generate financial analysis reports with exposure, reconciliation, variance, and proof layers directly consumable by drafting benches.

📝

Comprehensive A4 Reports & Drafts

Outputs arrive as paginated A4 legal draft previews — edit in place, add instructions, save versions, or export to DOCX/PDF.

🏛️

Structured GST Procedure

Workflow mapped to statutory proceedings: scrutiny, audit, inquiry, SCN, adjudication, review, recovery, refund, registration and appeals.

⌛

Amendment & Rate-Timeline Aware

Answers grounded strictly in the law as it stood on the disputed tax period, not today’s text pasted backwards.

💼

Word Environment (Word Add-in)

Draft and review directly inside Microsoft Word with live GSTArk citation validation and verified database lookup.

📨

PDF, Word & Email Output

Seamless multi-format export for formal dispatch, judicial filing, internal department notesheets, or client email briefs.

⚡

Targeted Folder Analysis & SCN Agents

Automated agents for SCN construction, issue analysis, and speaking adjudication orders reading directly from case records.

📋

Portal Summary Intelligence

Speaking SCN with DRC-01 summary, speaking OIO with DRC-07 summary, and DRC-08 rectification summaries alongside full legal drafts.

⚖️

GSTAT Litigation Workflows

Dedicated GSTAT filing packages: APL-05 / APL-06 / APL-07 logic, stay petitions, and written submissions without inappropriate DRC forms.

🔍

Verified Source Layer

247 sections, 213 rules, circulars, notifications, and 10,220+ verified judgments — missing authority flagged as unverified.

📁

Notesheet & Internal Note Support

Department-side notesheets for scrutiny, revision, recovery, and personal hearing stages integrated directly into the file.

Case Continuity

One case file that travels, stage to stage, until the matter is closed

A draft is never an orphan. It joins its case, and the case moves: scrutiny to notice, notice to reply, reply to adjudication, order to appeal. Every stage inherits the facts, the record and the history of the one before, in an append-only ledger nothing can rewrite.

✓
Seamless transfer of the matter between benches, no re-entry of facts
✓
Append-only case ledger: every event, dated and permanent
✓
Status, risk and next action computed live for every open matter
✓
Closed only at a definite outcome, and archived with its full history
Sample Matter Showcase
Case CASE-0041 · Sample Traders Pvt Ltd
Sample matter
N
DRC-01 received, s.74
14 Aug · exposure ₹2.89 Cr · clock armed
Trigger
↓
R
Reply drafted on the SCN Reply Bench
22 Aug · engines run · A4 filed
Drafted
↓
H
Personal hearing, adjudication stage
Due 28 Oct · brief prepared from the same file
Next
↓
O
Order, then acceptance or appeal
The file carries forward either way
Outcome
The dashboard for the clock

Every open matter on one ledger: bench, demand exposure, draft status, the limitation clock and the next required action, sorted by deadline urgency. Sample matters shown.
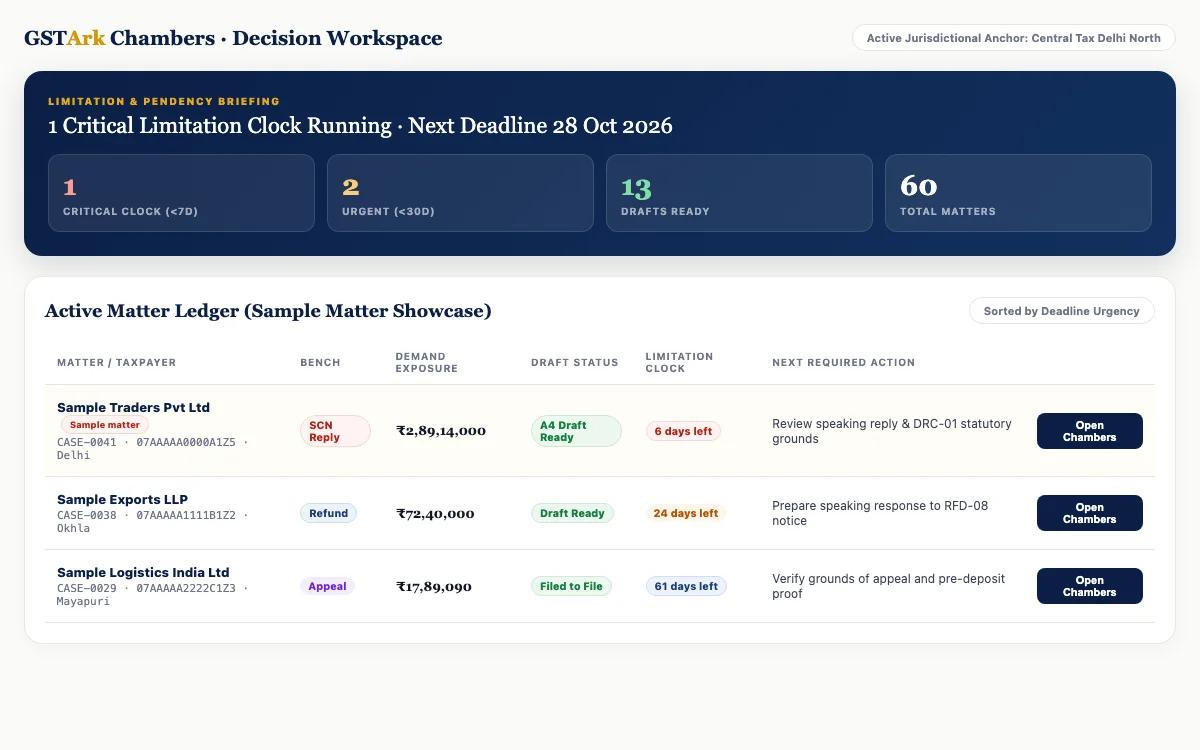
gstark.ai / dashboard · Sample matter showcase
GSTArk Chambers decision workspace dashboard: limitation and pendency briefing with 1 critical clock, 2 urgent, 13 drafts ready and 60 total matters, and the active matter ledger (sample matter showcase) listing Sample Traders Pvt Ltd, Sample Exports LLP and Sample Logistics India Ltd with bench, demand exposure, draft status, limitation clock and next required action
Decision Environment

Before you file, know how the other side moves.

The draft is the start, not the end. GSTArk runs decision intelligence engines around every draft: calculating success probability, measuring financial exposure, tracking the opponent's limitation clock, and scanning for omissions argued from both sides.
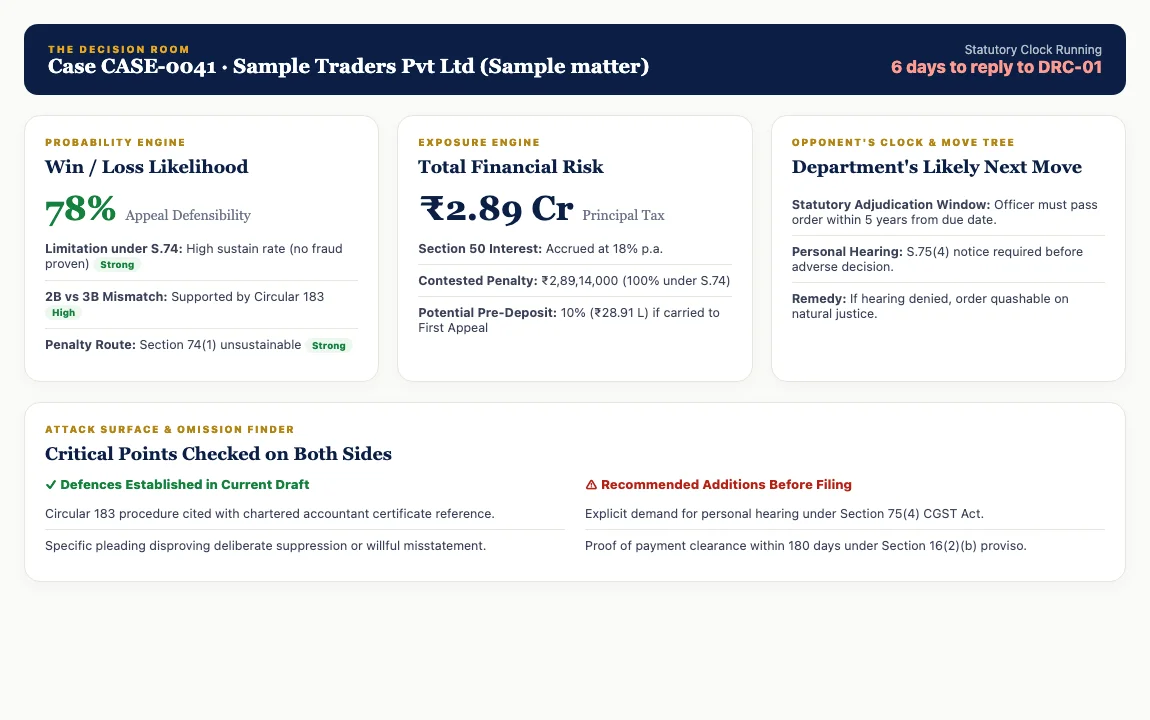
Verified Active Engines: Probability · Exposure · Opponent's Clock · Attack Surface · Omission Scanner · Notesheet. (No unbuilt money ladder or penalty matrix claims).
GSTArk Decision Room with Probability and Exposure Engines
Active Engine

Probability Engine

Calculates the appeal sustainability and defensibility probability for each legal ground individually based on precedent grounding.

Active Engine

Exposure Calculation

Separates principal tax demand from accrued Section 50 interest and statutory penalty assessments to model exact financial exposure.

Active Engine

Opponent's Limitation Clock

Tracks the departmental officer’s statutory deadlines under Section 73(10) and Section 74(11), highlighting when proceedings are time-barred.

Active Engine

Attack Surface & Omission Finder

Reviews drafts from both revenue and taxpayer perspectives to catch omitted statutory provisos, natural justice defects, and unaddressed facts.

Active Engine

Precedent Map & Citation Resolution

Resolves all cited case laws, circulars, and notifications against the verified corpus, flagging unverified authorities before finalization.

Active Engine

Notesheet Engine

Generates department-grade speaking notesheets and internal briefings that travel with the case file across proceeding stages.

Dual Workspaces

Built for both sides of GST practice.

Professionals need authority and reasoning. Taxpayers need clarity, defence, and compliance action. GSTArk supports both without mixing their workflows, and the same matter can be examined from either chair.

🏛️
Department Workflows

Revenue practice

Scrutiny notes, notices, adjudication orders, audit reports, summons, investigation memos, recovery notices, and departmental reasoning.

Scrutiny and assessment
Audit and inspection
Inquiry and investigation
Show Cause Notice (SCN)
Order in Original (OIO)
Review and revision
Recovery proceedings
Refund processing
Registration matters
GSTAT litigation
Notesheet and internal note
Financial analysis support
🏢
Practitioner & Taxpayer Workflows

Taxpayer practice

Replies to SCNs, appeal grounds, refund responses, reconciliation support, personal hearing submissions, and compliance corrections.

Reply to SCN / notice
Hearing and personal appearance
Appeal drafting
GSTAT — submissions and filings
Refund application and follow-up
Registration — application and objection
Recovery relief and stay
Evidence defence and document planning
Financial reconciliation and exposure
Limitation and natural justice challenge
APL-05 / APL-06 / APL-07 filings
IA / stay / condonation support
Taxpayer Practice · In DevelopmentComing soon

Your GST portal, read for you.

A read-only bridge in development for taxpayer accounts. Connect your portal once, fetch returns and notices automatically, detect discrepancies early, and feed the fetched records directly into the drafting benches without double entry.

Architecture Overview

How the Read-Only Bridge Works

Source Account
Taxpayer Portal

Notices, orders, GSTR-1, 3B, 2B and ledgers.

API + OTP
Security Layer
Consent & OTP

Taxpayer approves via OTP. Access will run through a licensed GST Suvidha Provider; zero password storage.

Read-Only
Intelligence
GSTArk Engine

Will match returns, find short payment, compute S.50 interest and check refunds.

Into benches
Direct Output
Drafting Benches

Populates SCN Reply, Reconciliation, and Refund benches so figures are not typed in again.

Core Capabilities in Development

What the portal bridge will do for taxpayers

Fetch Notices & Orders

Will fetch notices and orders directly from the taxpayer's GST portal account, with each notice's due date in view.

In Development

Three-Way Return Reconciliation

Will fetch returns and reconcile them: GSTR-1 against GSTR-3B, GSTR-2B against books of account, and ITC claimed against ITC available.

In Development

Short Payment & Interest Computation

Will find short tax payments across periods and compute the Section 50 interest on each shortfall.

In Development

Refund Eligibility Detection

Will identify refunds the taxpayer may claim under export turnover, inverted duty structure, or excess cash ledger balance.

In Development

Direct Bench Feeds (No Double Entry)

Will feed what it finds straight into the right bench (SCN reply, reconciliation, refund claim), so figures are not typed in again.

In Development
Security & Operational Architecture

How it works, stated plainly.

We designed this bridge with these safeguards. You retain complete ownership and control of your taxpayer account at all times.

01
Taxpayer-approved access

The taxpayer enables API access on gst.gov.in and approves each session with a one-time password (OTP).

02
Strictly read-only

GSTArk never files, amends, submits, or changes anything on the portal. It only reads records into your file.

03
Zero password exposure

GSTArk never asks for, receives, or stores your GST portal password under any circumstances.

04
Licensed GSP infrastructure

Access will run through a licensed GST Suvidha Provider.

05
Taxpayer side only

Built solely for taxpayer accounts and practitioners acting on behalf of taxpayers; not connected to department internal systems.

GSTArk is independent and is not affiliated with GSTN or any government body.
● Early Access Waitlist

Be first to test the Taxpayer Portal Bridge

The bridge is currently in closed development.

Request early access

Write to us and we will reply when early testing opens.

Knowledge Tree

The statute, grown as a living tree.

247 sections across CGST (190), IGST (28) and UTGST (29), organised in 39 statutory chapters (21 CGST + 9 IGST + 9 UTGST). Every section is a node, and every node carries its whole legal life.

CGST Act, 2017Ch. VInput Tax CreditRule · Rule 36, CGST Rules Documentary requirements and conditions for claiming input tax creditRule · Rule 37, CGST Rules Reversal of input tax credit in the case of non-payment of considerationRule · Rule 37A, CGST Rules Reversal of ITC in case of non-payment of tax by the supplier and re-availment thereofRules3Notification · Notification 22/2024-Central Tax, 2024-10-08 Notifies the special procedure under section 148 of the CGST Act for rectification of demand orders issued for contravention of section 16(4) of the said ActNotification · Notification 17/2024-Central Tax, 2024-09-27 Appoints. — (a) the date of publication of this notification in the Official Gazette, as the date on which the provisions of sections 118, 142, 148 and 150 of the said Act shall come into force; and (b) the 1st day of November, 2024, as the date on which the provisions of sections 114 to 117, 119 to 141, 143 to 147, 149 and 151 to 157 of the said Act shall come into force.Notification · Notification 28/2023-Central Tax, 2023-07-31 Appoints, — (a) the 1st day of October, 2023, as the date on which the provisions of sections 137 to 162 (except sections 149 to 154) of the said Act shall come into force; (b) the 1st day of August, 2023, as the date on which the provisions of sections 149 to 154 of the said Act shall come into force.Notification · Notification 18/2022-Central Tax, 2022-09-28 Appoints the 1st day of October, 2022, as the date on which the provisions of sections 100 to 114, except clause (c) of section 110 and section 111, of the said Act shall come into force.Notification · Notification 39/2021-Central Tax, 2021-12-21 Appoints the 1st day of January, 2022, as the date on which the provisions of sections 108, 109 and 113 to 122 of the said Act shall come into force.Notification · Notification 4/2021-Central Tax (Rate), 2021-06-14 Amends N. No. 11/2017-CT(R) so as to notify GST rates of various services as recommended by GST Council in its 44th meeting held on 12.06.2021Notification · Notification 2/2021-Central Tax (Rate), 2021-06-02 Amends N. No. 11/2017-CT(R) so as to notify CGST rates of various services as recommended by GST Council in its 43rd meeting held on 28.05.2021Notification · Notification 24/2021-Central Tax, 2021-06-01 Amends N. No. 14/2021 - CT in order to extend due date of compliances which fall during the period from “15.04.2021 to 29.06.2021” till 30.06.2021Notification · Notification 14/2021-Central Tax, 2021-05-01 Extends specified compliances falling between 15.04.2021 to 30.05.2021 till 31.05.2021 in exercise of powers under section 168A of CGST ActNotification · Notification 92/2020-Central Tax, 2020-12-22 Appoints the 1st day of January, 2021, as the date on which the provisions of sections 119, 120, 121, 122, 123, 124, 126, 127 and 131 of the said Act shall come into force.Notification · Notification 39/2020-Central Tax, 2020-05-05 Makes amendments in N. No. 11/2020 - CT, dt. 21.03.2020 regarding special procedure for corporate debtors undergoing the corporate insolvency resolution process under the Insolvency and Bankruptcy Code, 2016Notification · Notification 11/2020-Central Tax, 2020-03-21 Provides special procedure for corporate debtors undergoing the corporate insolvency resolution process under the Insolvency and Bankruptcy Code, 2016Notification · Notification 9/2017-Central Tax, 2017-06-28 Brings into force sec 44 of CGST Act, w.e.f. 01.07.2017Notifications13Circular · Circular 241/35/2024-GST, 2024-12-31 Clarification on availability of input tax credit as per clause (b) of sub- section (2) of section 16 of the Central Goods and Services Tax Act, 2017 in respect of goods which have been delivered by the supplier at his place of business under Ex-Works ContractCircular · Circular 237/31/2024-GST, 2024-10-15 Clarifying the issues regarding implementation of provisions of sub-section (5) and sub-section (6) in section 16 of CGST Act, 2017Circular · Circular 211/5/2024-GST, 2024-06-26 Clarification on time limit under Section 16(4) of CGST Act, 2017 in respect of RCM supplies received from unregistered personsCircular · Circular 193/5/2023-GST, 2023-07-17 Clarification to deal with difference in Input Tax Credit (ITC) availed in FORM GSTR-3B as compared to that detailed in FORM GSTR-2A for the period 01.04.2019 to 31.12.2021.Circular · Circular 195/7/2023-GST, 2023-07-17 Clarification on availability of ITC in respect of warranty replacement of parts and repair services during warranty period.Circular · Circular 183/15/2022-GST, 2022-12-27 Clarification to deal with difference in Input Tax Credit (ITC) availed in FORM GSTR-3B as compared to that detailed in FORM GSTR-2A for FY 2017-18 and 2018-19Circular · Circular 184/16/2022-GST, 2022-12-27 Clarification on the entitlement of input tax credit where the place of supply is determined in terms of the proviso to sub-section (8) of section 12 of the Integrated Goods and Services Tax Act, 2017Circular · Circular 171/3/2022-GST, 2022-07-06 Clarification on various issues relating to applicability of demand and penalty provisions under the Central Goods and Services Tax Act, 2017 in respect of transactions involving fake invoicesCircular · Circular 160/16/2021-GST, 2021-09-20 Clarification in respect of certain GST related issuesCircular · Circular 142/12/2020-GST, 2020-10-09 Clarification relating to application of sub-rule (4) of rule 36 of the CGST Rules, 2017 for the months of February, 2020 to August, 2020Circular · Circular 136/6/2020-GST, 2020-04-03 Clarification in respect of various measures announced by the Government for providing relief to the taxpayers in view of spread of Novel Corona Virus (COVID-19)Circular · Circular 112/31/2019-GST, 2019-10-03 Withdrawal of Circular No. 105/24/2019-GST dated 28.06.2019Circular · Circular 105/24/2019-GST, 2019-06-28 Withdrawn by 112/31/2019-GST ab initio Clarification on various doubts related to treatment of secondary or post-sales discounts under GSTCircular · Circular 72/46/2018-GST, 2018-10-26 Circular to clarify the procedure in respect of return of time expired drugs or medicinesCircular · Circular 24/24/2017-GST, 2017-12-21 Superseded by 125/44/2019-GST, in force until 2019-11-17 Manual filing and processing of refund claims on account of inverted duty structure, deemed exports and excess balance in electronic cash ledger- Reg.Circulars15Judgment · GST Appellate Tribunal, 2026-08-31 N. R. Builders v. Commissioner of Commercial Taxes, KarnatakaJudgment · GST Appellate Tribunal, 2026-08-27 Lucknow Test House v. Shashi Bhushan Singh, Additional Commissioner Grade-II, State Tax Lucknow & Ors.Judgment · GST Appellate Tribunal, 2026-08-21 Santhhome Latex Enterprises v. Commissioner of CGST, ThiruvananthapuramJudgment · GST Appellate Tribunal, 2026-08-21 Vijayan Sahadevan (Deceased) v. The Commissioner of Kerala State GST, ThiruvananthapuramJudgment · GST Appellate Tribunal, 2026-08-20 Anil Kumar Singh v. Director, S/O Sanjay Kumar Agarwallahar Patti Nehru Road Thakurganj Brkis 855116, Agarwala's Bitumex Private LimitedJudgment · GST Appellate Tribunal, 2026-07-31 Tata Unistore Limited v. Commissioner CGST & Ex., Navi MumbaiJudgment · Andhra Pradesh High Court, 2026-04-27 Sona Enterprises vs The Assistant Commissioner & OrsJudgment · Telangana High Court, 2026-04-21 Mahadev Hardware vs The Superintendent Of Central Tax Uppal ...Judgment · Delhi High Court, 2026-04-18 M/S Kanika Exports vs Union Of India & OrsJudgment · Bombay High Court, 2026-04-17 Parinee Realty Pvt Ltd vs Union Of IndiaJudgments28810 shownRule · Rule 38, CGST Rules Claim of credit by a banking company or a financial institutionRule · Rule 42, CGST Rules Manner of determination of input tax credit in respect of inputs or input services and reversal thereofRule · Rule 43, CGST Rules Manner of determination of input tax credit in respect of capital goods and reversal thereof in certain casesRules3Notification · Notification 17/2024-Central Tax, 2024-09-27 Appoints. — (a) the date of publication of this notification in the Official Gazette, as the date on which the provisions of sections 118, 142, 148 and 150 of the said Act shall come into force; and (b) the 1st day of November, 2024, as the date on which the provisions of sections 114 to 117, 119 to 141, 143 to 147, 149 and 151 to 157 of the said Act shall come into force.Notification · Notification 28/2023-Central Tax, 2023-07-31 Appoints, — (a) the 1st day of October, 2023, as the date on which the provisions of sections 137 to 162 (except sections 149 to 154) of the said Act shall come into force; (b) the 1st day of August, 2023, as the date on which the provisions of sections 149 to 154 of the said Act shall come into force.Notification · Notification 9/2017-Central Tax, 2017-06-28 Brings into force sec 44 of CGST Act, w.e.f. 01.07.2017Notifications3Circular · Circular 231/25/2024-GST, 2024-09-10 Clarification on availability of input tax credit in respect of demo vehiclesCircular · Circular 214/8/2024-GST, 2024-06-26 Clarification on the requirement of reversal of input tax credit in respect of the portion of the premium for life insurance policies which is not included in taxable valueCircular · Circular 216/10/2024-GST, 2024-06-26 Clarification in respect of GST liability and input tax credit (ITC) availability in cases involving Warranty/ Extended Warranty, in furtherance to Circular No. 195/07/2023-GST dated 17.07.2023Circular · Circular 217/11/2024-GST, 2024-06-26 Entitlement of ITC by the insurance companies on the expenses incurred for repair of motor vehicles in case of reimbursement mode of insurance claim settlementCircular · Circular 219/13/2024-GST, 2024-06-26 Clarification on availability of input tax credit on ducts and manholes used in network of optical fiber cables (OFCs) in terms of section 17(5) of the CGST Act, 2017Circular · Circular 172/4/2022-GST, 2022-07-06 Clarification on various issue pertaining to GSTCircular · Circular 92/11/2019-GST, 2019-03-07 Clarification on various doubts related to treatment of sales promotion schemes under GSTCircular · Circular 72/46/2018-GST, 2018-10-26 Circular to clarify the procedure in respect of return of time expired drugs or medicinesCircular · Circular 48/22/2018-GST, 2018-06-14 Clarifications of certain issues under GSTCircular · Circular 33/7/2018-GST, 2018-02-23 Directions under Section 168 of the CGST Act regarding non-transition of CENVAT credit under section 140 of CGST Act or non-utilization thereof in certain casesCirculars10Judgment · GST Appellate Tribunal, 2026-08-21 Santhhome Latex Enterprises v. Commissioner of CGST, ThiruvananthapuramJudgment · GST Appellate Tribunal, 2026-08-05 Commissioner CGST & Cx, Kolkata North v. M/s. Power Tech Global Private LimitedJudgment · GST Appellate Tribunal, 2026-07-17 DGAP v. Merit Magnum Construction (formerly M/s Vimal Builders)Judgment · Andhra Pradesh High Court, 2026-04-01 Golden Traders vs Special Secretary 1Had Considered The ...Judgment · Andhra Pradesh High Court, 2026-04-01 Golden Traders vs Special Secretary 1Had Considered The ...Judgment · Andhra Pradesh High Court, 2026-04-01 Golden Traders vs Special Secretary 1Had Considered The ...Judgment · Bombay High Court, 2026-03-10 Smruti Waghdhare vs Joint Director, Directorate General Of ...Judgment · Orissa High Court, 2026-01-22 M/S. Paradeep Phosphates Limited vs Additional CommissionerJudgment · Madras High Court, 2026-01-02 M/S.Nanban Container Lines Pvt Ltd vs The Deputy State Tax OfficerJudgment · Andhra Pradesh High Court, 2025-12-31 M/S. Seil Energy India Limited vs DeputyJudgments7010 shownCh. XIRefundsRule · Rule 82, CGST Rules Details of inward supplies of persons having Unique Identity NumberRule · Rule 89, CGST Rules Application for refund of tax, interest, penalty, fees or any other amountRule · Rule 90, CGST Rules AcknowledgementRule · Rule 91, CGST Rules Grant of provisional refundRule · Rule 92, CGST Rules Order sanctioning refundRule · Rule 93, CGST Rules Credit of the amount of rejected refund claimRule · Rule 95, CGST Rules Refund of tax to certain personsRule · Rule 96, CGST Rules Refund of integrated tax paid on goodsRule · Rule 96A, CGST Rules Rule 96ARule · Rule 96B, CGST Rules Recovery of refund of unutilised input tax credit or integrated tax paid on export of goods where export proceeds not realisedRule · Rule 96C, CGST Rules Bank Account for credit of refundRule · Rule 97A, CGST Rules Manual filing and processingRules12Notification · Notification 17/2024-Central Tax, 2024-09-27 Appoints. — (a) the date of publication of this notification in the Official Gazette, as the date on which the provisions of sections 118, 142, 148 and 150 of the said Act shall come into force; and (b) the 1st day of November, 2024, as the date on which the provisions of sections 114 to 117, 119 to 141, 143 to 147, 149 and 151 to 157 of the said Act shall come into force.Notification · Notification 15/2023-Central Tax (Rate), 2023-10-19 Amends N. No. 15/2017-CT(R), dt. 28.06.2017Notification · Notification 18/2023-Integrated Tax (Rate), 2023-10-19 Amends N. No 12/2017-IT(R), dt. 28.06.2017Notification · Notification 23/2023-Integrated Tax (Rate), 2023-10-19 Amends N. No 05/2017-IT(R), dt. 28.06.2017Notification · Notification 28/2023-Central Tax, 2023-07-31 Appoints, — (a) the 1st day of October, 2023, as the date on which the provisions of sections 137 to 162 (except sections 149 to 154) of the said Act shall come into force; (b) the 1st day of August, 2023, as the date on which the provisions of sections 149 to 154 of the said Act shall come into force.Notification · Notification 18/2022-Central Tax, 2022-09-28 Appoints the 1st day of October, 2022, as the date on which the provisions of sections 100 to 114, except clause (c) of section 110 and section 111, of the said Act shall come into force.Notification · Notification 20/2022-Central Tax, 2022-09-28 read with Corrigendum dt. 29.09.2022 Rescinded N. No. 20/2018 - CT, dt. 28.03.2018 w.e.f. 01.10.2022Notification · Notification 9/2022-Central Tax (Rate), 2022-07-13 Amends N. No. 5/2017-CT(R) - Restriction of ITC on certain goodsNotification · Notification 13/2022-Central Tax, 2022-07-05 Extends dates of specified compliances in exercise of powers under section 168A of CGST ActNotification · Notification 24/2021-Central Tax, 2021-06-01 Amends N. No. 14/2021 - CT in order to extend due date of compliances which fall during the period from “15.04.2021 to 29.06.2021” till 30.06.2021Notification · Notification 14/2021-Central Tax, 2021-05-01 Extends specified compliances falling between 15.04.2021 to 30.05.2021 till 31.05.2021 in exercise of powers under section 168A of CGST ActNotification · Notification 56/2020-Central Tax, 2020-06-27 Further extend period to pass order under Section 54(7) of CGST Act (Subs. N. No. 46/2020 - CT, dt. 09.06.2020)Notification · Notification 46/2020-Central Tax, 2020-06-09 Extends period to pass order under Section 54(7) of CGST Act.Notification · Notification 3/2019-Compensation Cess (Rate), 2019-09-30 Notifies the goods, the description of which is specified in column (3) of the Table below and falling under the tariff item, heading, sub-heading or Chapter, as the case may be, as specified in the corresponding entry in column (2) of the said Table, in respect of which no refund of unutilised input tax credit of compensation cess shall be allowed, where the credit has accumulated on account of rate of compensation cess on inputs being higher than the rate of compensation cess on the output supplies of such goods (other than nil rated or fully exempt supplies).Notification · Notification 39/2019-Central Tax, 2019-08-31 Appoints the 1st day of September, 2019, as the date on which the provisions of section 103 the said Act, shall come into force.Notification · Notification 20/2018-Central Tax (Rate), 2018-07-26 Amends N. No 05/2017-CT(R), dt. 28.06.2017 to give effect to the recommendations of the GST Council in 28th meeting held on 21.07.2018Notification · Notification 20/2018-Central Tax, 2018-03-28 Rescinded by 20/2022-Central Tax, in force until 2022-09-27 recinded vide 20/2022 - CT, dt. 28.09.2022 read with Corrigendum dated 29.09.2022 Extension of due date for filing of application for refund under section 55 by notified agenciesNotification · Notification 4/2018-Central Tax (Rate), 2018-01-25 Provides special procedure with respect to payment of tax by registered person supplying service by way of construction against transfer of development right and vice versaNotification · Notification 44/2017-Central Tax (Rate), 2017-11-14 Amends N. No. 5/2017-CT(R), dt. 28.06.2017 - Restriction of ITC on certain fabricsNotification · Notification 39/2017-Central Tax, 2017-10-13 Cross-empowers State Tax officers for processing and grant of refundNotification · Notification 37/2017-Central Tax, 2017-10-04 Extension of facility of LUT to all exportersNotification · Notification 29/2017-Central Tax (Rate), 2017-09-22 Amends N. No. 5/2017-CT(R), dt. 28.06.2017 to give effect to GST council decisions regarding restriction of refund on corduroy fabrics under sec 54(3)Notification · Notification 13/2017-Central Tax, 2017-06-28 Prescribes rate of interest under CGST Act, 2017 for the purpose of sec 50, 54 and 56Notification · Notification 15/2017-Central Tax (Rate), 2017-06-28 Supplies, which are not eligible for refund of unutilized ITC under CGST ActNotification · Notification 5/2017-Central Tax (Rate), 2017-06-28 Supplies of goods in respect of which no refund of unutilised input tax credit shall be allowed under sec 54(3)Notification · Notification 9/2017-Central Tax, 2017-06-28 Brings into force sec 44 of CGST Act, w.e.f. 01.07.2017Notifications26Circular · Circular 233/27/2024-GST, 2024-09-10 Clarification regarding regularization of refund of IGST availed in contravention of rule 96(10) of CGST Rules, 2017, in cases where the exporters had imported certain inputs without payment of integrated taxes and compensation cessCircular · Circular 226/20/2024-GST, 2024-07-10 Mechanism for refund of additional Integrated Tax (IGST) paid on account of upward revision in price of the goods subsequent to exportsCircular · Circular 197/9/2023-GST, 2023-07-17 Clarification on refund related issues.Circular · Circular 188/20/2022-GST, 2022-12-27 Prescribing manner of filing an application for refund by unregistered personsCircular · Circular 181/13/2022-GST, 2022-11-10 Clarification on refund related issuesCircular · Circular 172/4/2022-GST, 2022-07-06 Clarification on various issue pertaining to GSTCircular · Circular 173/5/2022-GST, 2022-07-06 Clarification on issue of claiming refund under inverted duty structure where the supplier is supplying goods under some concessional notificationCircular · Circular 175/7/2022-GST, 2022-07-06 Manner of filing refund of unutilized ITC on account of export of electricityCircular · Circular 168/24/2021-GST, 2021-12-30 Mechanism for filing of refund claim by the taxpayers registered in erstwhile Union Territory of Daman & Diu for period prior to merger with U.T. of Dadra & Nagar Haveli.Circular · Circular 166/22/2021-GST, 2021-11-17 Clarification on certain refund related issuesCircular · Circular 160/16/2021-GST, 2021-09-20 Clarification in respect of certain GST related issuesCircular · Circular 139/9/2020-GST, 2020-06-10 Clarification on refund related issuesCircular · Circular 137/7/2020-GST, 2020-04-13 Clarification in respect of certain challenges faced by the registered persons in implementation of provisions of GST LawsCircular · Circular 135/5/2020-GST, 2020-03-31 Clarification on refund related issuesCircular · Circular 131/1/2020-GST, 2020-01-23 Standard Operating Procedure (SOP) to be followed by exportersCircular · Circular 125/44/2019-GST, 2019-11-18 Fully electronic refund process through FORM GST RFD-01 and single disbursementCircular · Circular 110/29/2019-GST, 2019-10-03 Eligibility to file a refund application in FORM GST RFD-01 for a period and category under which a NIL refund application has already been filedCircular · Circular 111/30/2019-GST, 2019-10-03 Procedure to claim refund in FORM GST RFD-01 subsequent to favourable order in appeal or any other forumCircular · Circular 108/27/2019-GST, 2019-07-18 Clarification in respect of goods sent/taken out of India for exhibition or on consignment basis for export promotionCircular · Circular CORRIGENDUM:45/19/2018-GST:2019-07-18, 2019-07-18 Superseded by 125/44/2019-GST, in force until 2019-11-17 Corrigendum to Circular No. 45/19/2018-GST dated 30th May, 2018 issued vide F. No. CBEC/20/16/4/2018-GST - reg.Circular · Circular 106/25/2019-GST, 2019-06-29 Withdrawn by 176/8/2022-GST ab initio - Refund of taxes paid on inward supply of indigenous goods by retail outlets established at departure area of the international airport beyond immigration counters when supplied to outgoing international tourist against foreign exchangeCircular · Circular 104/23/2019-GST, 2019-06-28 Processing of refund applications in FORM GST RFD-01A submitted by taxpayers wrongly mapped on the common portalCircular · Circular 94/13/2019-GST, 2019-03-28 Superseded by 125/44/2019-GST, in force until 2019-11-17 Clarifications on refund related issues under GSTCircular · Circular 88/7/2019-GST, 2019-02-01 Changes in Circulars issued earlier under the CGST Act, 2017Circular · Circular 79/53/2018-GST, 2018-12-31 Superseded by 125/44/2019-GST, in force until 2019-11-17 Clarification on refund related issuesCircular · Circular 70/44/2018-GST, 2018-10-26 Superseded by 125/44/2019-GST, in force until 2019-11-17 Clarification on certain issues related to refundCircular · Circular 59/33/2018-GST, 2018-09-04 Superseded by 125/44/2019-GST, in force until 2019-11-17 Clarification on refund related issuesCircular · Circular 56/30/2018-GST, 2018-08-24 Clarification regarding removal of restriction of refund of accumulated ITC on fabricsCircular · Circular 48/22/2018-GST, 2018-06-14 Clarifications of certain issues under GSTCircular · Circular 40/14/2018-GST, 2018-04-06 Clarification on issues related to furnishing of Bond/Letter of Undertaking for exportsCircular · Circular 37/11/2018-GST, 2018-03-15 Superseded by 125/44/2019-GST, in force until 2019-11-17 Clarifications on exports related refund issuesCircular · Circular 24/24/2017-GST, 2017-12-21 Superseded by 125/44/2019-GST, in force until 2019-11-17 Manual filing and processing of refund claims on account of inverted duty structure, deemed exports and excess balance in electronic cash ledger- Reg.Circular · Circular 17/17/2017-GST, 2017-11-15 Superseded by 125/44/2019-GST, in force until 2019-11-17 Manual filing and processing of refund claims in respect of zero-rated supplies - reg.Circulars33Judgment · GST Appellate Tribunal, 2026-08-20 Anil Kumar Singh v. Director, S/O Sanjay Kumar Agarwallahar Patti Nehru Road Thakurganj Brkis 855116, Agarwala's Bitumex Private LimitedJudgment · GST Appellate Tribunal, 2026-06-04 Dow Chemical International Pvt. Ltd. vs Commissioner of State Tax, Mazgaon, MumbaiJudgment · Delhi High Court, 2026-04-28 Mahanadi Exporttek Pvt Ltd vs Union Of India & OrsJudgment · Bombay High Court, 2026-04-23 Chec Tpl Line 4 Joint Venture vs Union Of India And OrsJudgment · Bombay High Court, 2026-04-23 Chec Tpl Line 4 Joint Venture vs Union Of India And OrsJudgment · Delhi High Court, 2026-04-18 M/S Kanika Exports vs Union Of India & OrsJudgment · Bombay High Court, 2026-04-16 Interactive Brokers Software Services ... vs Union Of IndiaJudgment · Bombay High Court, 2026-04-16 Infinx Services Private Limited vs The Union Of India Thr The Secretary And ...Judgment · Rajasthan High Court, 2026-04-13 Arawali Engineers vs Union Of India (2026:Rj-Jd:17161-Db)Judgment · Calcutta High Court, 2026-04-02 Cbf Component Private Limited & Anr vs The Union Of India & OrsJudgments23910 shownRule · Rule 94, CGST Rules Order sanctioning interest on delayed refundsRules1Notification · Notification 28/2023-Central Tax, 2023-07-31 Appoints, — (a) the 1st day of October, 2023, as the date on which the provisions of sections 137 to 162 (except sections 149 to 154) of the said Act shall come into force; (b) the 1st day of August, 2023, as the date on which the provisions of sections 149 to 154 of the said Act shall come into force.Notification · Notification 13/2017-Central Tax, 2017-06-28 Prescribes rate of interest under CGST Act, 2017 for the purpose of sec 50, 54 and 56Notification · Notification 9/2017-Central Tax, 2017-06-28 Brings into force sec 44 of CGST Act, w.e.f. 01.07.2017Notifications3Circular · Circular 131/1/2020-GST, 2020-01-23 Standard Operating Procedure (SOP) to be followed by exportersCircular · Circular 79/53/2018-GST, 2018-12-31 Superseded by 125/44/2019-GST, in force until 2019-11-17 Clarification on refund related issuesCirculars2Judgment · Bombay High Court, 2026-04-16 Marathon Electric India Private ... vs Union Of IndiaJudgment · Bombay High Court, 2026-04-16 Marathon Electric India Private ... vs Union Of IndiaJudgment · Orissa High Court, 2026-01-22 M/S. Paradeep Phosphates Limited vs Additional CommissionerJudgment · Andhra Pradesh High Court, 2026-01-21 M/S. Awl Agri Business Limited vs Vkc FootstepsJudgment · Karnataka High Court, 2025-12-12 South Indian Oil Corporation vs The Assistant Commissioner Central TaxJudgment · Karnataka High Court, 2025-12-12 South Indian Oil Corporation vs The Assistant Commissioner Central TaxJudgment · Bombay High Court, 2025-12-09 Ma Agro Proprietor Mr Ashfak Jafar ... vs Dy Commissioner Of State Tax Sanpada 501Judgment · Bombay High Court, 2025-10-17 West India Continental Oils Fats Pvt. ... vs The Union Of IndiaJudgment · Gujarat High Court, 2025-09-19 Vineet Polyfab Pvt. Ltd vs Union Of IndiaJudgment · Delhi High Court, 2025-08-13 M/S Moms Cradle Private Limited vs The Union Of India & AnrJudgments5110 shownCh. XVDemands and RecoveryRule · Rule 142, CGST Rules Notice and order for demand of amounts payable under the ActRule · Rule 142A, CGST Rules Procedure for recovery of dues under existing lawsRules2Notification · Notification 17/2024-Central Tax, 2024-09-27 Appoints. — (a) the date of publication of this notification in the Official Gazette, as the date on which the provisions of sections 118, 142, 148 and 150 of the said Act shall come into force; and (b) the 1st day of November, 2024, as the date on which the provisions of sections 114 to 117, 119 to 141, 143 to 147, 149 and 151 to 157 of the said Act shall come into force.Notification · Notification 56/2023-Central Tax, 2023-12-28 Extends dates of specified compliances in exercise of powers under section 168A of CGST Act for adjudication of cases for the years 2018-19 and 2019-20Notification · Notification 13/2022-Central Tax, 2022-07-05 Extends dates of specified compliances in exercise of powers under section 168A of CGST ActNotification · Notification 24/2021-Central Tax, 2021-06-01 Amends N. No. 14/2021 - CT in order to extend due date of compliances which fall during the period from “15.04.2021 to 29.06.2021” till 30.06.2021Notification · Notification 14/2021-Central Tax, 2021-05-01 Extends specified compliances falling between 15.04.2021 to 30.05.2021 till 31.05.2021 in exercise of powers under section 168A of CGST ActNotification · Notification 9/2017-Central Tax, 2017-06-28 Brings into force sec 44 of CGST Act, w.e.f. 01.07.2017Notifications6Circular · Circular 250/7/2025-GST, 2025-06-24 Reviewing authority, Revisional Authority and Appellate Authority in respect of orders passed by Common Adjudicating Authority (CAA) for show cause notices issued by DGGICircular · Circular 239/33/2024-GST, 2024-12-04 Amendment to Circular No. 31/05/2018-GST, dated 9th February, 2018 on 'Proper officer under sections 73 and 74 of the Central Goods and Services Tax Act, 2017 and under the Integrated Goods and Services Tax Act, 2017'Circular · Circular 187/19/2022-GST, 2022-12-27 Clarification regarding the treatment of statutory dues under GST law in respect of the taxpayers for whom the proceedings have been finalised under Insolvency and Bankruptcy Code, 2016Circular · Circular 171/3/2022-GST, 2022-07-06 Clarification on various issues relating to applicability of demand and penalty provisions under the Central Goods and Services Tax Act, 2017 in respect of transactions involving fake invoicesCircular · Circular 169/1/2022-GST, 2022-03-12 Amendment to Circular No. 31/05/2018-GST, dated 9th February, 2018 on ‘Proper officer under sections 73 and 74 of the Central Goods and Services Tax Act, 2017 and under the Integrated Goods and Services Tax Act, 2017'Circular · Circular 76/50/2018-GST, 2018-12-31 Clarification on certain issues (sale by government departments to unregistered person; leviability of penalty under section 73(11) of the CGST Act; rate of tax in case of debit notes / credit notes issued under section 142(2) of the CGST Act; applicability of notification No. 50/2018-Central Tax; valuation methodology in case of TCS under Income Tax Act and definition of owner of goods) related to GST-Reg.Circular · Circular 31/5/2018-GST, 2018-02-09 Proper officer under sections 73 and 74 of the Central Goods and Services Tax Act, 2017 and under the Integrated Goods and Services Tax Act, 2017Circulars7Judgment · GST Appellate Tribunal, 2026-08-31 N. R. Builders v. Commissioner of Commercial Taxes, KarnatakaJudgment · GST Appellate Tribunal, 2026-08-27 Lucknow Test House v. Shashi Bhushan Singh, Additional Commissioner Grade-II, State Tax Lucknow & Ors.Judgment · GST Appellate Tribunal, 2026-08-21 Vijayan Sahadevan (Deceased) v. The Commissioner of Kerala State GST, ThiruvananthapuramJudgment · GST Appellate Tribunal, 2026-08-05 Commissioner CGST & Cx, Kolkata North v. M/s. Power Tech Global Private LimitedJudgment · GST Appellate Tribunal, 2026-07-31 Tata Unistore Limited v. Commissioner CGST & Ex., Navi MumbaiJudgment · Andhra Pradesh High Court, 2026-04-27 Sona Enterprises vs The Assistant Commissioner & OrsJudgment · Delhi High Court, 2026-04-23 M/S Ramada Engineering Industry vs Additional ...Judgment · Bombay High Court, 2026-04-22 Taiyo Nippon Sanso India Private ... vs Union Of IndiaJudgment · Gauhati High Court, 2026-04-21 WP(C)/5236/2022Judgment · Gauhati High Court, 2026-04-21 WP(C)/5163/2022Judgments56610 shownRule · Rule 142, CGST Rules Notice and order for demand of amounts payable under the ActRule · Rule 142A, CGST Rules Procedure for recovery of dues under existing lawsRules2Notification · Notification 17/2024-Central Tax, 2024-09-27 Appoints. — (a) the date of publication of this notification in the Official Gazette, as the date on which the provisions of sections 118, 142, 148 and 150 of the said Act shall come into force; and (b) the 1st day of November, 2024, as the date on which the provisions of sections 114 to 117, 119 to 141, 143 to 147, 149 and 151 to 157 of the said Act shall come into force.Notification · Notification 39/2021-Central Tax, 2021-12-21 Appoints the 1st day of January, 2022, as the date on which the provisions of sections 108, 109 and 113 to 122 of the said Act shall come into force.Notification · Notification 24/2021-Central Tax, 2021-06-01 Amends N. No. 14/2021 - CT in order to extend due date of compliances which fall during the period from “15.04.2021 to 29.06.2021” till 30.06.2021Notification · Notification 14/2021-Central Tax, 2021-05-01 Extends specified compliances falling between 15.04.2021 to 30.05.2021 till 31.05.2021 in exercise of powers under section 168A of CGST ActNotification · Notification 9/2017-Central Tax, 2017-06-28 Brings into force sec 44 of CGST Act, w.e.f. 01.07.2017Notifications5Circular · Circular 250/7/2025-GST, 2025-06-24 Reviewing authority, Revisional Authority and Appellate Authority in respect of orders passed by Common Adjudicating Authority (CAA) for show cause notices issued by DGGICircular · Circular 239/33/2024-GST, 2024-12-04 Amendment to Circular No. 31/05/2018-GST, dated 9th February, 2018 on 'Proper officer under sections 73 and 74 of the Central Goods and Services Tax Act, 2017 and under the Integrated Goods and Services Tax Act, 2017'Circular · Circular 171/3/2022-GST, 2022-07-06 Clarification on various issues relating to applicability of demand and penalty provisions under the Central Goods and Services Tax Act, 2017 in respect of transactions involving fake invoicesCircular · Circular 169/1/2022-GST, 2022-03-12 Amendment to Circular No. 31/05/2018-GST, dated 9th February, 2018 on ‘Proper officer under sections 73 and 74 of the Central Goods and Services Tax Act, 2017 and under the Integrated Goods and Services Tax Act, 2017'Circular · Circular 31/5/2018-GST, 2018-02-09 Proper officer under sections 73 and 74 of the Central Goods and Services Tax Act, 2017 and under the Integrated Goods and Services Tax Act, 2017Circulars5Judgment · GST Appellate Tribunal, 2026-08-21 Santhhome Latex Enterprises v. Commissioner of CGST, ThiruvananthapuramJudgment · GST Appellate Tribunal, 2026-08-21 Vijayan Sahadevan (Deceased) v. The Commissioner of Kerala State GST, ThiruvananthapuramJudgment · GST Appellate Tribunal, 2026-08-05 Commissioner CGST & Cx, Kolkata North v. M/s. Power Tech Global Private LimitedJudgment · GST Appellate Tribunal, 2026-07-31 Tata Unistore Limited v. Commissioner CGST & Ex., Navi MumbaiJudgment · Andhra Pradesh High Court, 2026-04-27 Jawaharlal Nehru Technological ... vs Joint CommissionerJudgment · Andhra Pradesh High Court, 2026-04-27 Sona Enterprises vs The Assistant Commissioner & OrsJudgment · Delhi High Court, 2026-04-23 M/S Ramada Engineering Industry vs Additional ...Judgment · Bombay High Court, 2026-04-17 Parinee Realty Pvt Ltd vs Union Of IndiaJudgment · Rajasthan High Court, 2026-04-16 M/S Gyankeer Tobacco Products Pvt. Ltd vs Additional Commissioner ...Judgment · Bombay High Court, 2026-04-15 Deepak Chechani Prop. Of Deevyam Exim vs State Of Maharashtra And AnrJudgments40410 shown
RulesNotificationsCircularsJudgmentshollow: superseded, withdrawn or rescinded, as the corpus records it (13)Click a section or a twig for its list · hover or tap a leaf for its title

Every leaf is a link read from GSTArk's database for that section; nothing on the tree is illustrative. Rules, notifications and circulars are drawn in full; for judgments the ten most recent verified ones are drawn and the badge carries the full count.

CGST Act · Section 16

s.16 · Eligibility and conditions for taking input tax credit

3 rules · 13 notifications · 15 circulars · 288 judgments

Rules

3
  1. Rule 36
    Documentary requirements and conditions for claiming input tax credit
  2. Rule 37
    Reversal of input tax credit in the case of non-payment of consideration
  3. Rule 37A
    Reversal of ITC in case of non-payment of tax by the supplier and re-availment thereof

Notifications

13
  1. 22/2024-Central Tax2024-10-08
    Notifies the special procedure under section 148 of the CGST Act for rectification of demand orders issued for contravention of section 16(4) of the said Act
  2. 17/2024-Central Tax2024-09-27
    Appoints. — (a) the date of publication of this notification in the Official Gazette, as the date on which the provisions of sections 118, 142, 148 and 150 of the said Act shall come into force; and (b) the 1st day of November, 2024, as the date on which the provisions of sections 114 to 117, 119 to 141, 143 to 147, 149 and 151 to 157 of the said Act shall come into force.
  3. 28/2023-Central Tax2023-07-31
    Appoints, — (a) the 1st day of October, 2023, as the date on which the provisions of sections 137 to 162 (except sections 149 to 154) of the said Act shall come into force; (b) the 1st day of August, 2023, as the date on which the provisions of sections 149 to 154 of the said Act shall come into force.
  4. 18/2022-Central Tax2022-09-28
    Appoints the 1st day of October, 2022, as the date on which the provisions of sections 100 to 114, except clause (c) of section 110 and section 111, of the said Act shall come into force.
  5. 39/2021-Central Tax2021-12-21
    Appoints the 1st day of January, 2022, as the date on which the provisions of sections 108, 109 and 113 to 122 of the said Act shall come into force.
  6. 4/2021-Central Tax (Rate)2021-06-14
    Amends N. No. 11/2017-CT(R) so as to notify GST rates of various services as recommended by GST Council in its 44th meeting held on 12.06.2021
  7. 2/2021-Central Tax (Rate)2021-06-02
    Amends N. No. 11/2017-CT(R) so as to notify CGST rates of various services as recommended by GST Council in its 43rd meeting held on 28.05.2021
  8. 24/2021-Central Tax2021-06-01
    Amends N. No. 14/2021 - CT in order to extend due date of compliances which fall during the period from “15.04.2021 to 29.06.2021” till 30.06.2021
  9. 14/2021-Central Tax2021-05-01
    Extends specified compliances falling between 15.04.2021 to 30.05.2021 till 31.05.2021 in exercise of powers under section 168A of CGST Act
    Amended by 24/2021-Central Tax
  10. 92/2020-Central Tax2020-12-22
    Appoints the 1st day of January, 2021, as the date on which the provisions of sections 119, 120, 121, 122, 123, 124, 126, 127 and 131 of the said Act shall come into force.
  11. 39/2020-Central Tax2020-05-05
    Makes amendments in N. No. 11/2020 - CT, dt. 21.03.2020 regarding special procedure for corporate debtors undergoing the corporate insolvency resolution process under the Insolvency and Bankruptcy Code, 2016
  12. 11/2020-Central Tax2020-03-21
    Provides special procedure for corporate debtors undergoing the corporate insolvency resolution process under the Insolvency and Bankruptcy Code, 2016
    Amended by 39/2020-Central Tax
  13. 9/2017-Central Tax2017-06-28
    Brings into force sec 44 of CGST Act, w.e.f. 01.07.2017

Circulars

15
  1. 241/35/2024-GST2024-12-31
    Clarification on availability of input tax credit as per clause (b) of sub- section (2) of section 16 of the Central Goods and Services Tax Act, 2017 in respect of goods which have been delivered by the supplier at his place of business under Ex-Works Contract
  2. 237/31/2024-GST2024-10-15
    Clarifying the issues regarding implementation of provisions of sub-section (5) and sub-section (6) in section 16 of CGST Act, 2017
  3. 211/5/2024-GST2024-06-26
    Clarification on time limit under Section 16(4) of CGST Act, 2017 in respect of RCM supplies received from unregistered persons
  4. 193/5/2023-GST2023-07-17
    Clarification to deal with difference in Input Tax Credit (ITC) availed in FORM GSTR-3B as compared to that detailed in FORM GSTR-2A for the period 01.04.2019 to 31.12.2021.
  5. 195/7/2023-GST2023-07-17
    Clarification on availability of ITC in respect of warranty replacement of parts and repair services during warranty period.
  6. 183/15/2022-GST2022-12-27
    Clarification to deal with difference in Input Tax Credit (ITC) availed in FORM GSTR-3B as compared to that detailed in FORM GSTR-2A for FY 2017-18 and 2018-19
  7. 184/16/2022-GST2022-12-27
    Clarification on the entitlement of input tax credit where the place of supply is determined in terms of the proviso to sub-section (8) of section 12 of the Integrated Goods and Services Tax Act, 2017
  8. 171/3/2022-GST2022-07-06
    Clarification on various issues relating to applicability of demand and penalty provisions under the Central Goods and Services Tax Act, 2017 in respect of transactions involving fake invoices
  9. 160/16/2021-GST2021-09-20
    Clarification in respect of certain GST related issues
  10. 142/12/2020-GST2020-10-09
    Clarification relating to application of sub-rule (4) of rule 36 of the CGST Rules, 2017 for the months of February, 2020 to August, 2020
  11. 136/6/2020-GST2020-04-03
    Clarification in respect of various measures announced by the Government for providing relief to the taxpayers in view of spread of Novel Corona Virus (COVID-19)
  12. 112/31/2019-GST2019-10-03
    Withdrawal of Circular No. 105/24/2019-GST dated 28.06.2019
  13. 105/24/2019-GST2019-06-28
    Clarification on various doubts related to treatment of secondary or post-sales discounts under GST
    Withdrawn by 112/31/2019-GST ab initio
  14. 72/46/2018-GST2018-10-26
    Circular to clarify the procedure in respect of return of time expired drugs or medicines
  15. 24/24/2017-GST2017-12-21
    Manual filing and processing of refund claims on account of inverted duty structure, deemed exports and excess balance in electronic cash ledger- Reg.
    Superseded by 125/44/2019-GST, in force until 2019-11-17

Judgments

288 · 10 most recent shown
  1. GST Appellate Tribunal2026-08-31
    N. R. Builders v. Commissioner of Commercial Taxes, Karnataka
  2. GST Appellate Tribunal2026-08-27
    Lucknow Test House v. Shashi Bhushan Singh, Additional Commissioner Grade-II, State Tax Lucknow & Ors.
  3. GST Appellate Tribunal2026-08-21
    Santhhome Latex Enterprises v. Commissioner of CGST, Thiruvananthapuram
  4. GST Appellate Tribunal2026-08-21
    Vijayan Sahadevan (Deceased) v. The Commissioner of Kerala State GST, Thiruvananthapuram
  5. GST Appellate Tribunal2026-08-20
    Anil Kumar Singh v. Director, S/O Sanjay Kumar Agarwallahar Patti Nehru Road Thakurganj Brkis 855116, Agarwala's Bitumex Private Limited
  6. GST Appellate Tribunal2026-07-31
    Tata Unistore Limited v. Commissioner CGST & Ex., Navi Mumbai
  7. Andhra Pradesh High Court2026-04-27
    Sona Enterprises vs The Assistant Commissioner & Ors
  8. Telangana High Court2026-04-21
    Mahadev Hardware vs The Superintendent Of Central Tax Uppal ...
  9. Delhi High Court2026-04-18
    M/S Kanika Exports vs Union Of India & Ors
  10. Bombay High Court2026-04-17
    Parinee Realty Pvt Ltd vs Union Of India
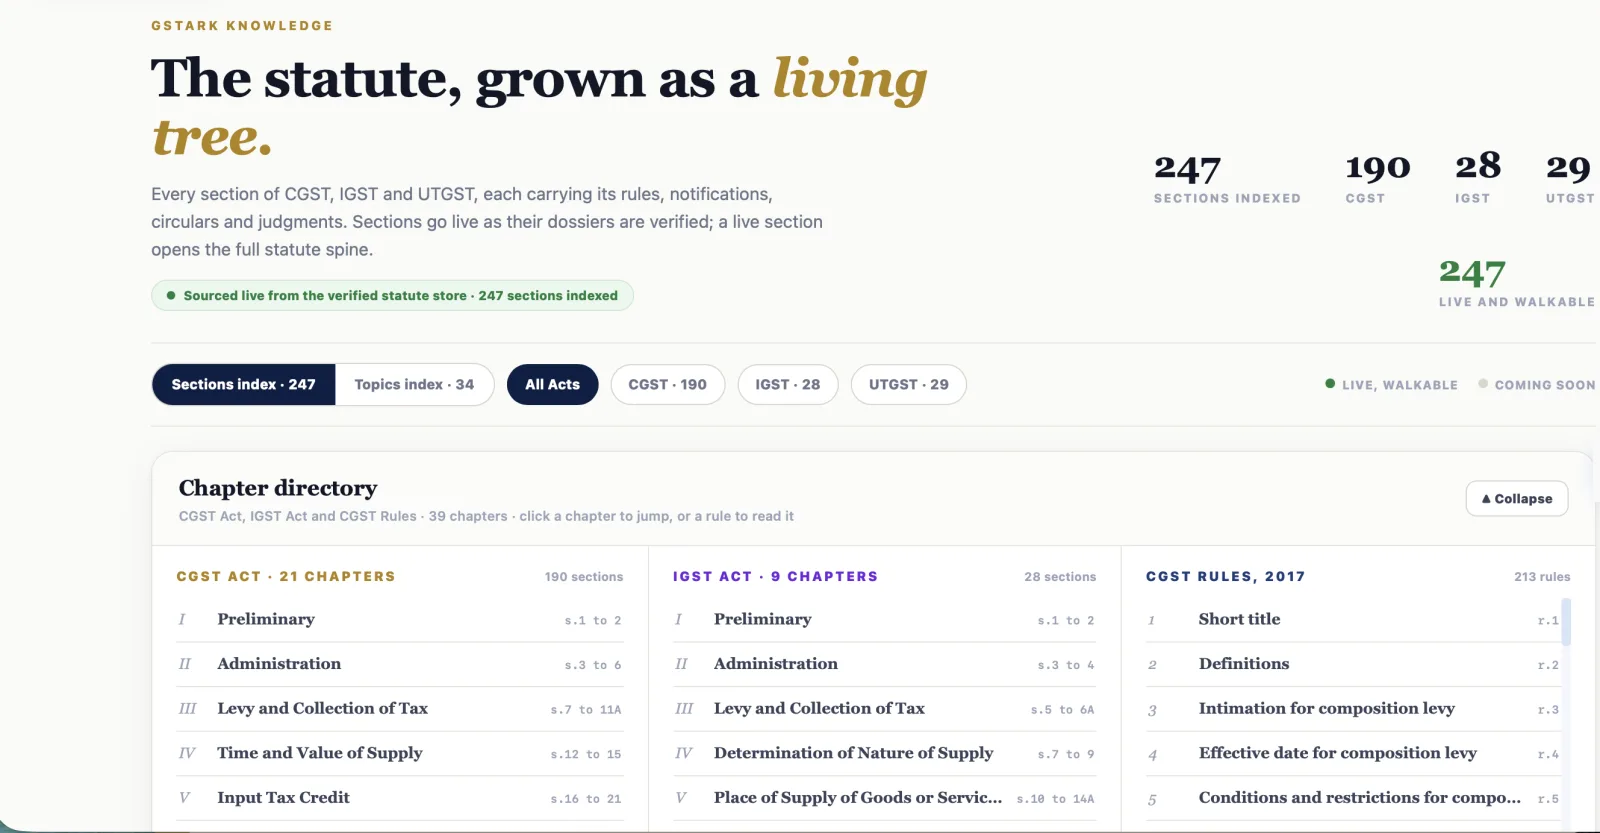
See all 288 →
gstark.ai / knowledge-tree
GSTArk Knowledge Tree page: the statute, grown as a living tree; 247 sections indexed (190 CGST, 28 IGST, 29 UTGST), all 247 live and walkable, with the chapter directory for the CGST Act, the IGST Act and the CGST Rules
Verified Statutory Foundation: 247 Sections · 213 CGST Rules · 10,220 Verified Judgments · 1,223 Notifications · 265 Circulars · 3,233 AAR / AAAR Rulings.

A dossier on every section

The rules made under it, the notifications that shaped it, the circulars that explain it and the judgments that tested it, all counted and attached.

The statute spine

Open a section and walk its full anatomy, sub-sections, provisos and conditions, with its rules hanging off the spine where they attach.

Read the source itself

A reading drawer opens the full text of any circular, notification or judgment, gazette-style, beside a plain-language gloss.

Verified store, not scraped text

Everything in the tree resolves against GSTArk's verified database; drafts cite from here, so citations trace back to source.

Amendment timeline

Each node knows its versions, so you read the section as it stood on the date your matter turns on.

Neighbours and cross-links

Move to adjacent sections and follow references across Acts without losing your place.

Workflow Architecture

From uploaded record to defensible draft.

GSTArk is a connected output system. Each step feeds the next — from bench selection through decision intelligence to editable A4 output. Users do not prompt. They select, review and refine.

One card, one document

Choose your instrument.

Each bench lists its instruments as cards: the primary instrument first, its supporting documents beside it. A card opens the guided input workspace, joins the case as a draft on the matter's timeline on first save, and returns every claim for your verification before anything issues.
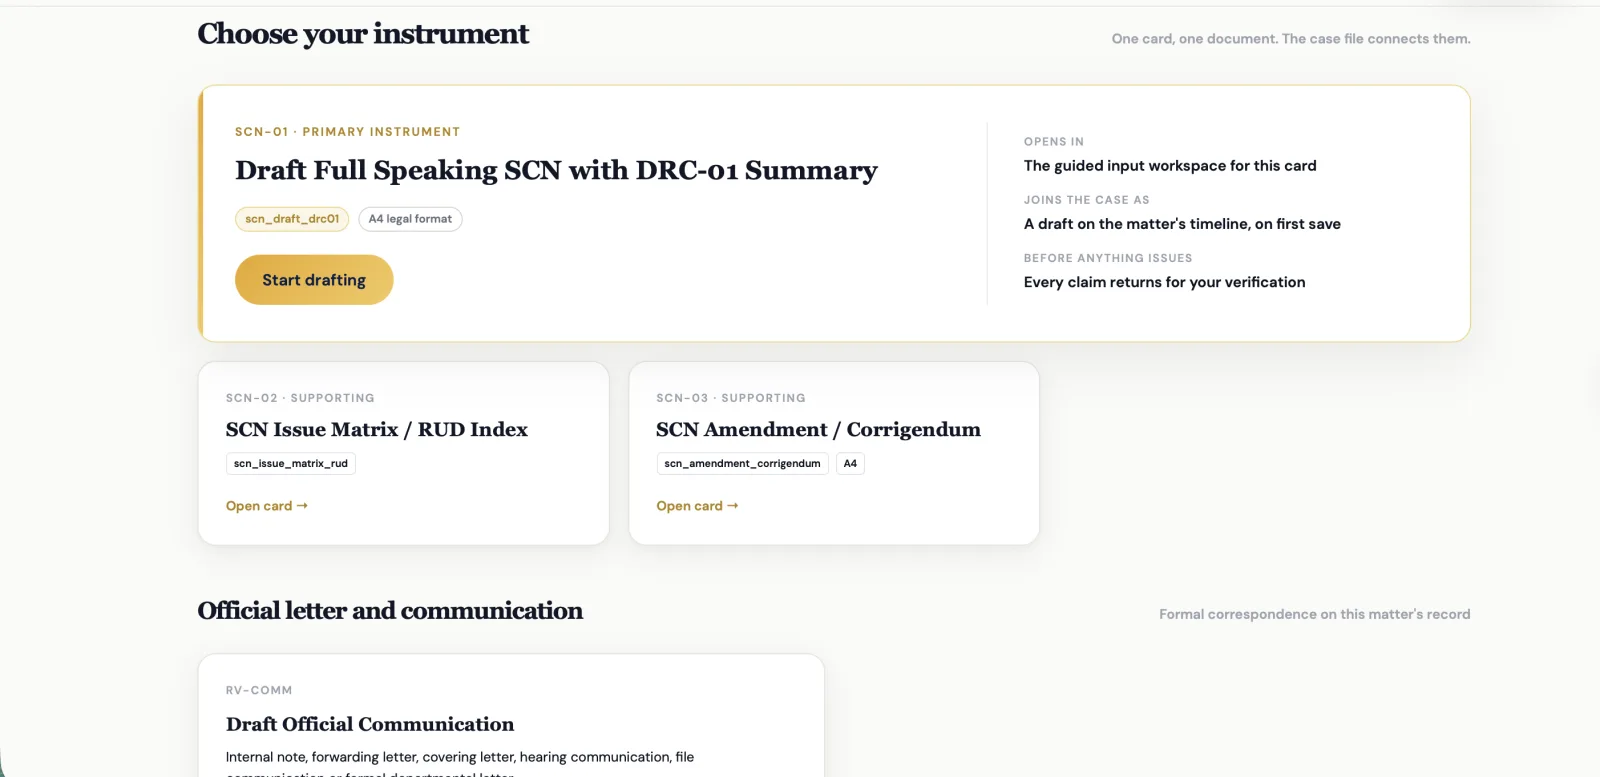
gstark.ai / revenue · SCN bench · Choose your instrument
GSTArk SCN bench, choose your instrument: SCN-01 Draft Full Speaking SCN with DRC-01 Summary as the primary instrument, SCN-02 SCN Issue Matrix / RUD Index and SCN-03 SCN Amendment / Corrigendum as supporting cards, then official letter and communication
01

Select Bench & Upload

Choose the matter type from structured GST workflow benches — scrutiny, SCN, OIO, audit, appeal, GSTAT, refund, registration, recovery or financial analysis. Upload notices, ledgers, or returns without a blank prompt.

Step 1 of 4
02

Extract & Analyse Position

System extracts issues, amounts, tax periods, and missing facts. GSTArk applies built-in expert logic — limitation, natural justice, evidence sufficiency, mens rea, litigation risk, and document gaps.

Step 2 of 4
03

Verify Grounding in Law

Relevant law and source materials are retrieved from the verified GST database of 247 sections and 213 rules, strictly as the law stood on the relevant tax period date.

Step 3 of 4
04

Draft, Decide & Finalise

Receive an exact A4 paginated legal draft with citations and confidence markers, surrounded by decision engines. Refine in place, save versions, and export directly to DOCX or PDF.

Step 4 of 4
Agents and Automation

Point an agent at a folder. Get a report, not a summary.

GSTArk's agents work the way an office works: on files. Give one a folder of returns, notices and worksheets and it returns analysis fit for the case file: figures reconciled, anomalies flagged, sources cited. Every result lands for human review, always.

🗂️

Folder analysis agents

Reconciliation, ITC trail, e-way analytics and more: agents in development that read your records and prepare structured, citable reports.

⏰

Scheduled tasks

Daily limitation sweep, weekly pendency digest, amendment watch on the sections your matters touch. Set the cadence once; the work arrives.

🧩

Skills, yours to add

Load your office's drafting conventions and checklists as skills; every bench and agent respects them.

🛡️

Twelve agents in development

Specialized intelligence agents spanning revenue and taxpayer lifecycles. Every agent result lands for human review, always.

Roster In Development

Twelve agents in development across both practices

Human review mandatory on all outputs
Department & Revenue Agents (6)
Scrutiny Agent
Scrutiny & Audit

Reads returns & mismatch data; prepares ASMT-style notes & scrutiny findings.

In Development
Audit Para Agent
Audit & Audit Para

Analyses audit observations and financial records to draft audit paras & SCN notes.

In Development
Financial Risk Agent
Financial Analysis

Reads P&L, balance sheets & ledgers to detect GST exposure across periods.

In Development
SCN Builder Agent
SCN Construction

Combines scrutiny, audit & financial findings into unified single or multi-issue SCNs.

In Development
Adjudication Agent
Adjudication / OIO

Reads SCN, reply, and hearing notes to prepare issue-wise findings for speaking orders.

In Development
Order Drafting Agent
Order / Ruling

Prepares speaking A4 orders for OIO, Commissioner Appeals, AAR and AAAR.

In Development
Taxpayer & Practitioner Defence Agents (6)
SCN Defence Agent
Notice & SCN Reply

Extracts allegations, identifies procedural defects & drafts structured replies.

In Development
Audit Reply Agent
Audit / Scrutiny Reply

Prepares point-wise replies to audit observations with supporting statutory authorities.

In Development
Financial Defence Agent
Financial Document Defence

Prepares financial counter-analysis, reconciliation exhibits & compliance schedules.

In Development
Hearing Submission Agent
Hearing Defence

Prepares written submissions, hearing briefs and documentary evidence compilation.

In Development
Appeal Agent
Order Analysis & Appeal

Identifies appealable defects in adverse orders, drafting grounds & pre-deposit filings.

In Development
Advance Ruling Agent
Advance Ruling Applicant

Assesses AAR suitability and prepares advance ruling applications & hearing submissions.

In Development
Trust Layer

Anti-hallucination is not a feature. It is the foundation.

In GST litigation, a wrong citation can damage professional standing. Every conclusion must have a stated confidence level with its basis. Every legal reference must resolve against primary statutory records. Every procedural risk must be identified before submission.

✓Verified source retrieval before legal analysis
✓Citation verification against primary sources
✓A stated confidence level, with its basis, on every conclusion
✓Missing document and procedural defect alerts
Multi-Model AI Architecture

Model access matched to task depth and plan.

GSTArk routes work through suitable AI models for drafting, analysis and document processing, while keeping all outputs inside GSTArk’s verification and citation discipline. Premium high-token models are controlled through higher plans, recharge credits or custom access — they are not unlimited at standard tiers.

“
“I spent twelve years inside indirect tax administration writing these notices, hearing these replies and drafting these orders. GSTArk is that experience, built into benches: it knows what the department will do next, because I did it.”
Founder, GSTArk · Former CGST officer, 12 years in indirect tax administration · Every legal skill and prompt framework curated from practice
About GSTArk

Institutional legal intelligence for GST practice.

Built with former CGST officers, practising advocates and GST litigation specialists who work GST matters. GST decision-making requires access to verified legal intelligence, not just document drafting.

Working on GST proceedings, we saw that officers, professionals and taxpayers struggled with three core challenges: understanding complete GST positions across amendments, evaluating litigation sustainability, and preparing defensible actions backed by verifiable evidence.

GSTArk is our response. A GST intelligence infrastructure platform combining verified statutory research, procedural analysis, pattern intelligence, and appellate awareness into one unified chambers.

Live Statutory Corpus (Database Query)
Live DB Connect
10,259
Judgments
1,257
Notifications
274
Circulars
3,233
AAR / AAAR

Our Principles

Verification First

Every citation is checked against GSTArk's corpus; what is not found is flagged.

Evidence Always

No arbitrary outputs. Citations and reasons shown with every draft.

Transparency Complete

Users understand exactly why a position is strong or weak.

Defensibility Always

Shows the weak points of a position before you file.

Desktop Application

A dedicated desktop chambers for serious drafting.

Work directly in a focused, low-latency environment on macOS and Windows with native file system access for your case records, folders, and offline knowledge tree caching.

● Desktop app, coming soon

Native macOS and Windows desktop builds are currently in testing.

Request early access

Write to us and we will reply when early testing opens.

Plans & Pricing

Start with GST workflows. Scale as you need.

All plans give access to GSTArk's structured workflow system. Higher plans and recharge credits unlock more capacity, advanced benches and controlled premium-model access.

⚠High-token premium models not included. Recharge credits required for premium-model calls.
Start free

7-Day Trial

Explore selected GSTArk® workflow benches at no cost.

Free7 days
  • ✓Access to selected workflow benches
  • ✓Limited generations
  • ✓Basic model access only
  • ✓Limited export and preview access
Light usage

Starter

For individual taxpayers and light GST drafting needs.

₹499/month
  • ✓Basic GST workflow bench access
  • ✓Quick drafts and selected replies
  • ✓Limited monthly generations
  • ✓Basic model access only
  • ✓Recharge required for heavy usage
Most popularRecommended

Professional

For CAs, advocates, consultants and regular GST professionals.

₹999/month
  • ✓More workflow bench access
  • ✓Editable A4 legal output
  • ✓Appeal, reply and GSTAT support within limits
  • ✓Standard model access
  • ✓Recharge required for premium-model tasks
Advanced access

Premium

For active GST professionals with high-volume drafting needs.

₹1,499/month
  • ✓Higher usage limits
  • ✓Advanced workflow benches
  • ✓Financial analysis access within fair-use limits
  • ✓Controlled premium-model credits where available
  • ✓Priority output quality
Controlled premium-model credits where available. Not unlimited premium-model usage.
High volume

Advanced

For high-volume GST practitioners and small firms with intensive drafting needs.

₹1,999/month
  • ✓All workflow benches — no access restrictions
  • ✓Higher generation limits than Premium
  • ✓Full financial analysis access
  • ✓Expanded premium-model credit allocation
  • ✓Priority output quality
  • ✓Suitable for small-firm and multi-matter use
Expanded premium-model credit allocation. Higher than ₹1,499 plan. Not unlimited premium-model usage.
Flexible top-up

Recharge Credits

Add-on credits for extra capacity beyond your plan.

Add-on
  • ✓Extra generations
  • ✓Heavy document processing
  • ✓Premium-model calls where available
  • ✓Large context analysis
  • ✓Additional financial analysis runs
For organisations

Custom Plan

For firms, tax teams and departmental users with specific requirements.

Custom
  • ✓Custom usage limits
  • ✓Custom model access configuration
  • ✓Bulk document processing
  • ✓Team workflows
  • ✓Dedicated source setup
  • ✓Onboarding and training support

Start with GST workflows, not blank AI prompts.

Choose the matter type, let GSTArk apply built-in GST intelligence, then edit the A4 draft, notesheet or report. Every output travels with the case file to a definite outcome.